In this guide
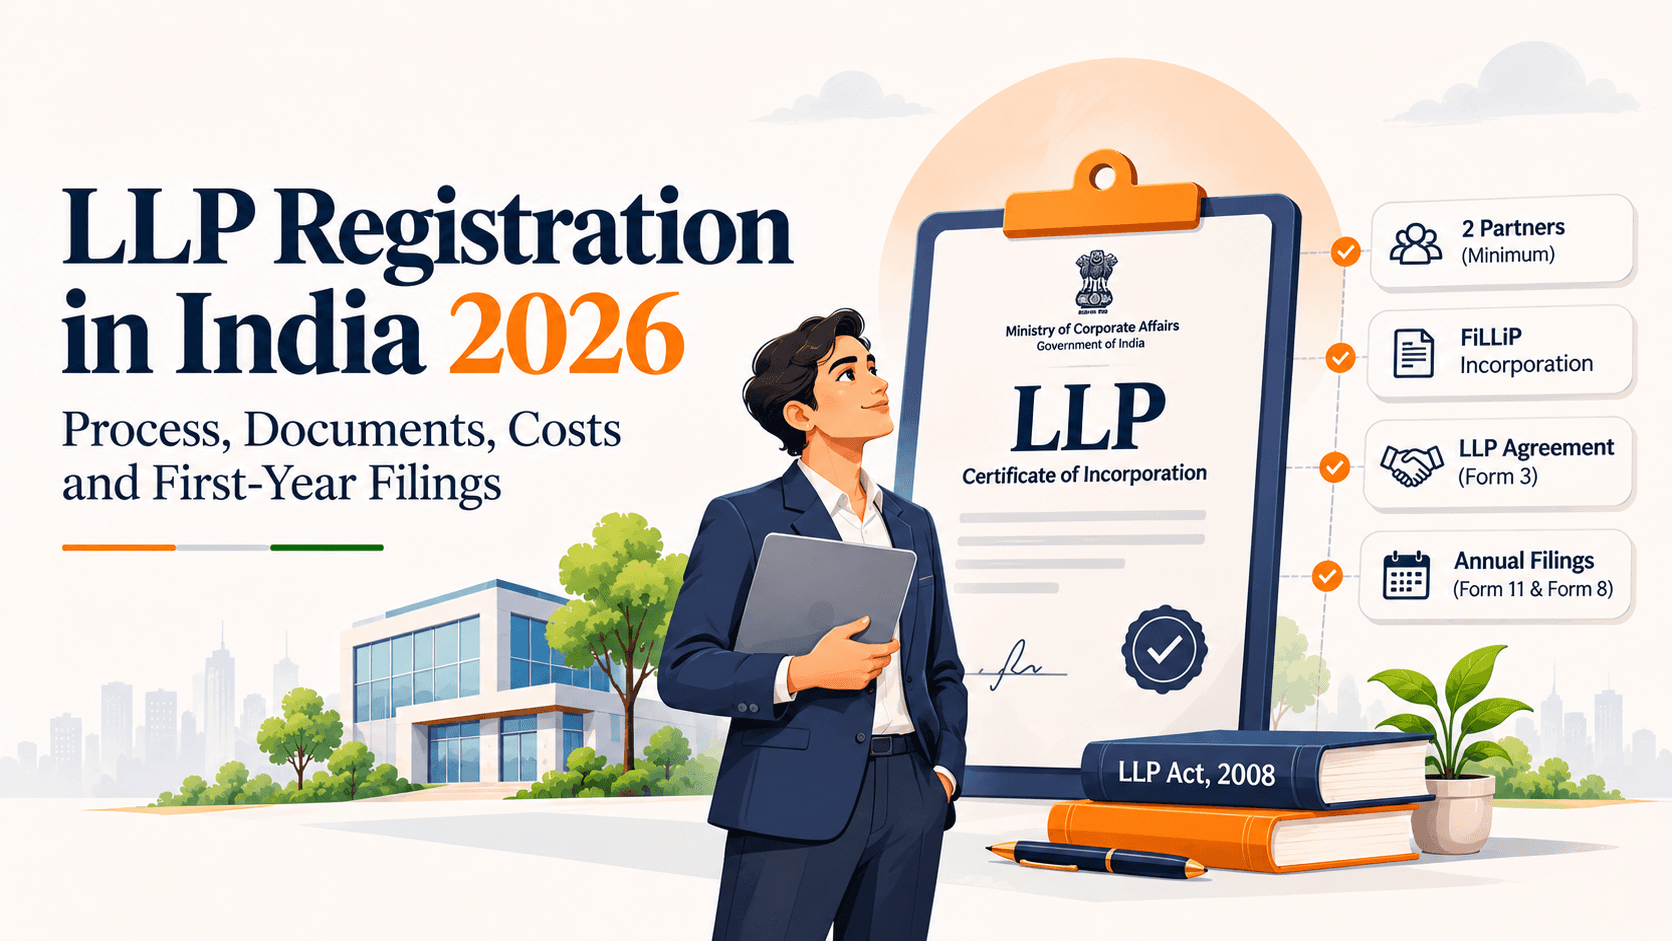
To register an LLP in India, you need at least two partners and two designated partners, with at least one designated partner resident in India (having stayed in India for at least 120 days during the financial year). You reserve a name, file the FiLLiP web incorporation form on the MCA21 V3 portal, and then file your LLP agreement in Form 3 within 30 days of incorporation.
This guide is for founders, professionals and small partner-led businesses who have already decided that an LLP may suit them. It also covers what many short guides leave out: the audit limits, annual filings, partner TDS rules and late fees that begin after registration.
Is an LLP the Right Structure for You?
An LLP combines limited liability with the flexibility of a partnership. It usually suits businesses owned and run by their partners, where internal terms are set by agreement and outside equity funding is unlikely.
| Your situation | Is an LLP a good fit? | What to think about |
|---|---|---|
| Consulting, agency or professional firm with active partners | Often yes | Agree on profit share, remuneration and exit terms in the LLP agreement. |
| Family or partner-owned trading business | Often yes | Check tax, audit needs, 10% partner TDS and how partners will take money out. |
| Startup planning angel or VC funding | Often no | Investors usually prefer shares, so compare a Private Limited Company. |
| Business planning employee stock options | Often no | Share-based companies are the more familiar route. |
| Solo founder | No | An LLP needs at least 2 partners. Compare an OPC or a proprietorship. |
If you are still deciding, read our full comparison of Private Limited vs LLP in 2026. Changing structure later can create legal, tax and paperwork costs, so choose with your 2–3 year plan in mind.
Who Can Register an LLP in India?
The Limited Liability Partnership Act, 2008 sets the basic structure:
- At least 2 partners (Section 6). There is no maximum limit on the number of partners.
- At least 2 designated partners (Section 7), who must be individuals. They carry the main legal and filing responsibilities.
- At least 1 designated partner must be resident in India. Following the LLP (Amendment) Act, 2021, “resident in India” means a person who has stayed in India for at least 120 days during the financial year (reduced from the earlier 182-day requirement).
- A company or another LLP (body corporate) can be a partner. If it acts as a designated partner, it appoints an individual nominee.
- Each designated partner needs a Designated Partner Identification Number (DPIN) or Director Identification Number (DIN)—they are interchangeable—and a Class 3 Digital Signature Certificate (DSC) for signing filings.
There is no fixed minimum capital contribution for an LLP. Under Section 32 of the LLP Act and Rule 23 of the LLP Rules, 2009, a partner's contribution can be in cash or in kind—including tangible, intangible, movable or immovable property, or other benefits such as promissory notes or contracts for services performed. If partners contribute non-cash assets, the value must be accounted for and certified by a practising Chartered Accountant, Cost Accountant or approved valuer.
Even though there is no minimum floor, decide your total contribution carefully: it directly determines your MCA incorporation fee, stamp duty, late-fee slab, and whether a statutory audit is required.
What Documents Do You Need for LLP Registration?
Most delays come from details that do not match. Names, dates of birth and addresses should be identical across PAN, ID proof and the application.
Checklist: For each partner
- [ ] PAN card (for Indian nationals) or Passport (for foreign nationals)
- [ ] Identity proof (Voter ID, Passport, Driving Licence or Aadhaar)
- [ ] Address proof (Bank statement, electricity bill, mobile bill or telephone bill, not older than 2 months)
- [ ] Recent passport-size photograph, email address and mobile number
- [ ] Class 3 Digital Signature Certificate (DSC) for designated partners
- [ ] Signed consent to act as a designated partner / partner (Form 9 details captured via FiLLiP)
Checklist: For the registered office
- [ ] Rent or lease agreement, or ownership proof
- [ ] Recent utility bill (electricity, gas, water or telephone bill not older than 2 months) showing the premises address
- [ ] Property owner's No-Objection Certificate (NOC) permitting use as the registered office
- [ ] Latitude and longitude coordinates of the registered office (mandatory in the MCA21 V3 FiLLiP address block)
Checklist: For the LLP
- [ ] 1 or 2 proposed LLP names
- [ ] Description of the main business activity and NIC code
- [ ] Total contribution amount and each partner's share
- [ ] Profit- and loss-sharing ratio
- [ ] Draft LLP agreement (for Form 3)
Foreign partners or NRIs living outside India may need notarised and apostilled (or consularised) identity and address proofs, depending on their country. Allow extra time for this.
How to Register an LLP: Step by Step
Step 1: Get Digital Signature Certificates
Designated partners sign MCA web forms electronically, so arrange their Class 3 Digital Signature Certificates (DSCs) and complete MCA V3 user profile registration first. Check that the name on each DSC matches the partner's PAN.
Step 2: Reserve the LLP name
You can reserve the name beforehand using the RUN-LLP (Reserve Unique Name – LLP) web service on the MCA21 V3 portal or apply directly inside the FiLLiP incorporation form. A name can be rejected if it is too close to an existing company, LLP or registered trademark. Keep a second option ready, and do not order branding until the name is approved.
Tip: Search the MCA and IP India trademark records before you apply. If you plan to build a brand, read our trademark registration service page as well.
Step 3: File the FiLLiP form
FiLLiP (Form for incorporation of Limited Liability Partnership) is the integrated web-based incorporation form on the MCA21 V3 portal. It captures the proposed name, business activity, registered office (with latitude and longitude), partners, contribution and designated partners. Under the LLP (Second Amendment) Rules, 2022, FiLLiP allows allotment of DPIN/DIN for up to 5 individual designated partners who do not already hold one (increased from the earlier limit of 2), and automatically processes the LLP's PAN and TAN allotment alongside incorporation.
Step 4: Respond to any queries
The Central Registration Centre (CRC) / Registrar may ask for clarifications or mark the form for resubmission. Common reasons include unclear business activity, weak utility bill proof or mismatched partner details.
Step 5: Receive the Certificate of Incorporation
Once approved, the Registrar issues the Certificate of Incorporation (Form 16) containing your LLP Identification Number (LLPIN), along with the LLP's PAN and TAN. Processing typically takes 7 to 15 working days (about 1 to 3 weeks) when documents are clean, though portal load or resubmissions can extend this. No adviser can guarantee a fixed government approval date, so plan with a range.
Step 6: File the LLP agreement in Form 3
Execute your LLP agreement on non-judicial stamp paper (stamp duty depends on the state where the registered office is located and the total capital contribution) and file it in Form 3 within 30 days of incorporation (Section 23(2) and Rule 21).
If you do not execute an agreement, or where the agreement is silent on any matter, the default mutual rights and duties in the First Schedule of the LLP Act, 2008 automatically apply—such as equal profit sharing regardless of capital contributed—which may not match what the partners intended.
A good LLP agreement should cover:
- Contribution and profit-sharing ratio
- Partner remuneration and interest on capital clauses (essential if you want tax deductions under Income Tax rules)
- Roles, voting rights and decision-making
- Admitting a new partner, and how a partner resigns or exits
- What happens if a partner dies or is unable to continue
- How the LLP handles disputes or closes down
What Does LLP Registration Cost?
There is no single price that applies to everyone. A useful quote separates statutory government fees from professional fees, so you can see what you are paying for.
| Cost item | What affects it | What to ask |
|---|---|---|
| MCA filing fee (Annexure A) | Total partner contribution (starts at ₹500 for contribution up to ₹1 lakh, scaling up with contribution) | Is the FiLLiP and Form 3 MCA fee included in the quote? |
| Stamp duty on the LLP agreement | State of registration and total contribution | Which state's stamp duty and notarisation were assumed? |
| Digital Signature Certificates | Number of designated partners and certifying authority | How many Class 3 DSCs (with token, if needed) are included? |
| Professional fees | Drafting the LLP agreement, number of partners, foreign partners | Are Form 3 drafting/filing and any CRC resubmissions covered? |
| Registered office documents | Owned, rented or shared premises | What proof or NOC format do you need? |
| First-year compliance | Accounts, audit, Form 11, Form 8, partner TDS, tax return | What happens after the Certificate of Incorporation arrives? |
What Happens After LLP Registration?
Registration is only the start. These are the main statutory items to plan for:
| Item | When | Note |
|---|---|---|
| Form 3 (LLP agreement) | Within 30 days of incorporation | Also needed within 30 days whenever the LLP agreement is amended. |
| Bank account and partner contribution | Soon after incorporation | Deposit each partner's agreed contribution through banking channels. |
| PAN, TAN and GST review | At the start | PAN/TAN arrive with incorporation; GST depends on activity and turnover. |
| Form 11 (annual return) | By 30 May each year (within 60 days of FY end) | Signed by 2 DPs; requires certification by a Practising Company Secretary if turnover exceeds ₹5 crore or contribution exceeds ₹50 lakh (Rule 25(2)). |
| Form 8 (Statement of Account & Solvency) | By 30 October each year (within 30 days from 6 months of FY end) | Requires 2 DPs' DSCs and certification by an auditor / practising CA, CS or CMA (Rule 24). |
| Income tax return (ITR-5) | 31 July (non-audit) or 31 October (audit cases; extended to 21 November 2026 for AY 2026-27) | Mandatory every year even if the LLP had zero income. |
| Statutory audit (Rule 24(8)) | Yearly, if limits are crossed | Required only if annual turnover exceeds ₹40 lakh OR total partner contribution exceeds ₹25 lakh. |
| Designated Partner KYC (DIR-3 KYC Web) | Once every 3 consecutive financial years (by 30 June) | Under G.S.R. 943(E) effective 31 March 2026, applies to all DPIN/DIN holders; contact changes must still be updated within 30 days. |
Note on first-year filings: If your LLP is incorporated on or after 1 October of a year (for example, 15 November 2026), Section 2(1)(l) of the LLP Act allows you to close your first financial year either on the upcoming 31 March (31 March 2027) or on 31 March of the next calendar year (31 March 2028) for MCA Form 11 and Form 8 purposes, though income tax still follows the standard April–March tax year.
Not sure which registrations apply? Our guide on when GST registration is required is a good next step.
How Is an LLP Taxed (Including the New 10% Partner TDS Rule)?
An LLP is taxed as a partnership firm at a flat 30% income tax rate (plus 12% surcharge where taxable income exceeds ₹1 crore, and 4% health and education cess), and is subject to Alternate Minimum Tax (AMT) at 18.5% where applicable. It does not have a lower optional rate like the 22% corporate regime available to domestic companies.
Three practical tax rules affect how partners withdraw money:
- Partner's share of post-tax profit is exempt: Once the LLP pays tax on its profits, a partner's share of the profit is exempt from income tax in the partner's hands (Section 10(2A) of the Income-tax Act, 1961 / Schedule II of the Income-tax Act, 2025, effective 1 April 2026) and is not subject to TDS.
- Deduction for partner remuneration and interest: An LLP can reduce its taxable profit by paying working-partner remuneration and interest on partner capital (up to 12% simple interest p.a.), provided both are explicitly authorised by the LLP agreement and stay within the statutory book-profit limits (Section 40(b) of the 1961 Act / Section 35 of the Income-tax Act, 2025).
- 10% TDS on payments to partners above ₹20,000: Under Section 194T of the Income-tax Act, 1961 (effective 1 April 2025) and Section 393(3) (Table Sl. No. 7) of the Income-tax Act, 2025 (effective 1 April 2026), every LLP must deduct 10% TDS on any salary, remuneration, commission, bonus or interest paid or credited to a partner once the aggregate for that partner exceeds ₹20,000 in a financial year.
What Are the Late Fees for LLP Form 8 and Form 11?
Be careful with this one, because many websites still repeat the old pre-2022 rule of ₹100 per day. Since the Limited Liability Partnership (Amendment) Rules, 2022 took effect on 1 April 2022 (substituting Annexure A of the LLP Rules, 2009), the additional fee for late filing of LLP forms (including Form 3, Form 8 and Form 11) is a slab-based multiple of the normal filing fee, with lower multiples for Small LLPs. It applies to each delayed form separately:
| Period of delay | Small LLP (additional fee) | Other than Small LLP (additional fee) |
|---|---|---|
| Up to 15 days | 1 time of normal filing fee | 1 time of normal filing fee |
| More than 15 days and up to 30 days | 2 times of normal filing fee | 4 times of normal filing fee |
| More than 30 days and up to 60 days | 4 times of normal filing fee | 8 times of normal filing fee |
| More than 60 days and up to 90 days | 6 times of normal filing fee | 12 times of normal filing fee |
| More than 90 days and up to 180 days | 10 times of normal filing fee | 20 times of normal filing fee |
| More than 180 days and up to 360 days | 15 times of normal filing fee | 30 times of normal filing fee |
| Beyond 360 days | 15 times of normal fee + ₹10 per day for every day beyond 360 days | 30 times of normal fee + ₹20 per day for every day beyond 360 days |
Under Section 2(1)(ta) of the LLP Act, a “Small LLP” is an LLP whose contribution does not exceed ₹25 lakh and whose turnover for the immediately preceding financial year does not exceed ₹40 lakh. Because the normal filing fee for Form 8 or Form 11 ranges from ₹50 (for contribution up to ₹1 lakh) to ₹200 (for contribution above ₹10 lakh), the portal's additional fee in the early slabs is much lower than ₹100/day.
However, separate civil adjudication penalties apply under Sections 34(5) and 35(2) (₹100 per day of default, capped at ₹1,00,000 for the LLP and ₹50,000 per designated partner, reduced by half for Small or Start-up LLPs under Section 76A if not rectified after notice).
Two more points are easy to miss:
- MCA's October 2026 relief (General Circular 05/2026) for AOC-4 and MGT-7 applies only to companies. It does not cover LLP Form 8 or Form 11.
- The Companies Compliance Facilitation Scheme, 2026 (CCFS-2026) also applied only to companies and did not cover LLPs.
Common Mistakes in LLP Registration
- Choosing an LLP when you already know you want equity investors or ESOPs.
- Adding a designated partner only to meet the two-person rule, without explaining the compliance responsibility.
- Using a generic agreement that omits working-partner remuneration or interest clauses (which disallows those tax deductions).
- Missing the 30-day Form 3 deadline after incorporation.
- Forgetting to deduct 10% TDS on partner salary or capital interest once a partner crosses ₹20,000 in the year.
- Assuming a small or inactive LLP does not have to file Form 11 and Form 8.
- Finalising branding before the name is approved on the MCA portal.
Frequently Asked Questions
How many people are needed to register an LLP?
You need at least two partners. At least two of them must be individuals acting as designated partners, and at least one designated partner must be resident in India, having stayed in India for at least 120 days during the financial year. There is no maximum number of partners.
Is there a minimum capital for an LLP?
No fixed minimum contribution applies. Partners decide the amount, and under Section 32 it can be in cash or in kind, including tangible or intangible property or other benefits properly valued and accounted for. Contribution affects MCA incorporation fees, state stamp duty, late-fee slabs and whether a statutory audit is required.
How long does LLP registration take?
In practice, LLP registration usually takes 7 to 15 working days once partner KYC and registered-office documents are ready. The exact time depends on DSC verification, name approval, Registrar queries and portal processing. Foreign partners can take longer because their documents may require notarisation or an apostille.
Is an audit compulsory for every LLP?
No. A statutory audit under the LLP Rules is required only if annual turnover exceeds ₹40 lakh or total partner contribution exceeds ₹25 lakh. Below both limits, an audit under the LLP Act is not required, though the LLP must still keep proper books and file Form 8 and Form 11 every year.
Can an LLP raise funds from investors?
An LLP cannot issue equity shares, so typical angel or venture-capital funding rounds do not fit it well. An investor would have to join as a partner, which most institutional investors avoid. If you expect to raise equity soon, compare a Private Limited Company first.
What happens if an LLP does not file Form 8 or Form 11?
Late filings attract slab-based additional fees, from 1 time up to 15 times the normal fee for a Small LLP or 30 times for other LLPs, plus ₹10 or ₹20 per day beyond 360 days. ROC adjudication penalties may also apply, and an LLP with overdue Form 8 or Form 11 cannot apply for strike-off in Form 24 until pending returns are filed.
Final Takeaway
LLP registration in India is straightforward when the partners agree on the important points first: who contributes what, who signs as a designated partner, how profits and remuneration are shared, and how someone can leave. Treat the LLP agreement seriously, file Form 3 within 30 days, and put Form 11 (30 May) and Form 8 (30 October) on your calendar from day one.
Planning to register an LLP?
AarambhGrow Advisory can help you compare structures, organise your documents and prepare your LLP filing.
Sources & legal note
This article is educational and should not be treated as a substitute for legal, tax or secretarial advice. Rules, fees and portal processes can change. Review the latest official requirements before filing.
- MCA portal and current notices
- Limited Liability Partnership Act, 2008 (as amended by the LLP (Amendment) Act, 2021
- LLP (Amendment) Rules, 2022 (Annexure A late-fee multiplier slabs effective 1 April 2022)
- LLP (Second Amendment) Rules, 2022 (FiLLiP 5 DPIN limit and PAN/TAN integration)
- CCFS-2026 coverage